Streetwear is no longer a subculture. How big it has become, though, depends entirely on whose report you buy, and the gap is wide enough to matter. Fortune Business Insights sizes the 2026 global market at US$397.97bn, about €365bn, growing 7.95% a year. Mordor Intelligence sizes the same market at US$218.3bn, about €200bn, growing 3.94%. One is 82% larger than the other.
Which series this page uses
We use the Fortune Business Insights series on this page because its regional breakdown is published in full, and we flag the Mordor figures wherever they contradict it. Both are converted from USD at roughly 1.09 to the euro, so the EUR amounts move with the exchange rate. Who is buying, where they buy, what drives the growth, and where Portugal sits in the value chain all follow.
Heads up: We're Portugal Clothing Factory, a group of 80 documented Portuguese clothing factories. The market data is sourced; the production data, archetype patterns, and cohort signals come from 200+ Portuguese streetwear placements between 2021 and 2026. EUR throughout.
Key Takeaways
- Market size estimates disagree by 82%: US$398bn in 2026 (Fortune Business Insights, 7.95% CAGR) against US$218bn (Mordor Intelligence, 3.94%). Treat either as an order of magnitude
- Asia Pacific leads at 36.33% of the 2025 market (US$134.8bn), ahead of North America at 26.80% and Europe at 20.78%
- Gen Z consumers are 1.5x more likely to purchase streetwear than older demographics
- Offline retail still held 54.62% of streetwear revenue in 2025, so online is nearer 45% than the 65% commonly quoted
- Limited editions and AI-powered design are the two fastest-growing trends
- Portuguese MOQs of 100-300 pieces enable small-brand entry into the €365B market
- Tight 3-5 style launches consistently outperform 10+ style debuts in our order book, measured by reorder rate rather than revenue, which we cannot see
Try it free: Pressure-test your streetwear cost with our garment cost calculator before committing to volumes. 60 seconds, no email required.
How Big Is the Global Streetwear Market in 2026?
On the Fortune Business Insights series the market was US$371.09bn in 2025, is US$397.97bn in 2026, and reaches US$734.05bn by 2034 at a 7.95% CAGR. That is roughly €340bn, €365bn and €673bn at 1.09 USD to the euro. On the Mordor Intelligence series the same market runs US$210.03bn, US$218.3bn and US$264.76bn by 2031, a 3.94% CAGR.
Both houses sell paid research and neither publishes its sampling frame, so we cannot tell you which is right. What we can tell you is that an 82% disagreement between the two leading estimates means no streetwear market-size figure should carry weight in a business plan, including the ones on this page. Use them for direction and order of magnitude, nothing finer.
Citation Capsule: Streetwear market estimates diverge sharply. Fortune Business Insights puts the global market at US$397.97bn in 2026 (about €365bn), rising to US$734.05bn by 2034 at a 7.95% CAGR. Mordor Intelligence puts the same 2026 market at US$218.3bn (about €200bn) at a 3.94% CAGR. The larger estimate is 82% above the smaller, so any single streetwear market figure should be read as an order of magnitude.
What's fueling this growth?
Three forces are converging. First, streetwear has absorbed luxury fashion's customer base. Second, direct-to-consumer brands have multiplied access points. Third, social media has turned every consumer into a potential brand ambassador.
The growth isn't just volume. Average order values have climbed as streetwear brands push into premium pricing tiers. A hoodie that sold for €55 three years ago now commands €85-€120 at indie labels. Consumers accept the markup when the brand story is strong enough.
Year-by-year market trajectory
| Year | Fortune Business Insights | Mordor Intelligence | Gap |
|---|---|---|---|
| 2025 | US$371.09bn (~€340bn) | US$210.03bn (~€193bn) | +77% |
| 2026 | US$397.97bn (~€365bn) | US$218.3bn (~€200bn) | +82% |
| 2031 | not published for this year | US$264.76bn (~€243bn) | — |
| 2034 | US$734.05bn (~€673bn) | not published for this year | — |
| Stated CAGR | 7.95% | 3.94% | 2.0x |
Fortune Business Insights, Streetwear Market (2025) and Mordor Intelligence, Streetwear Market (2025), as each publishes them. EUR figures are our conversions at 1.09 USD to the euro and move with the rate. Interpolated years have been removed: an earlier version of this table showed €420bn for 2028, €490bn for 2030 and €580bn for 2032, none of which either house publishes. They were our own CAGR extrapolations presented as forecasts.
Both series agree on direction. They disagree on pace by a factor of two, which is the honest summary: streetwear is growing, and the category has become a default wardrobe choice for a generation, but anyone quoting you a precise market size is quoting one house and ignoring the other.
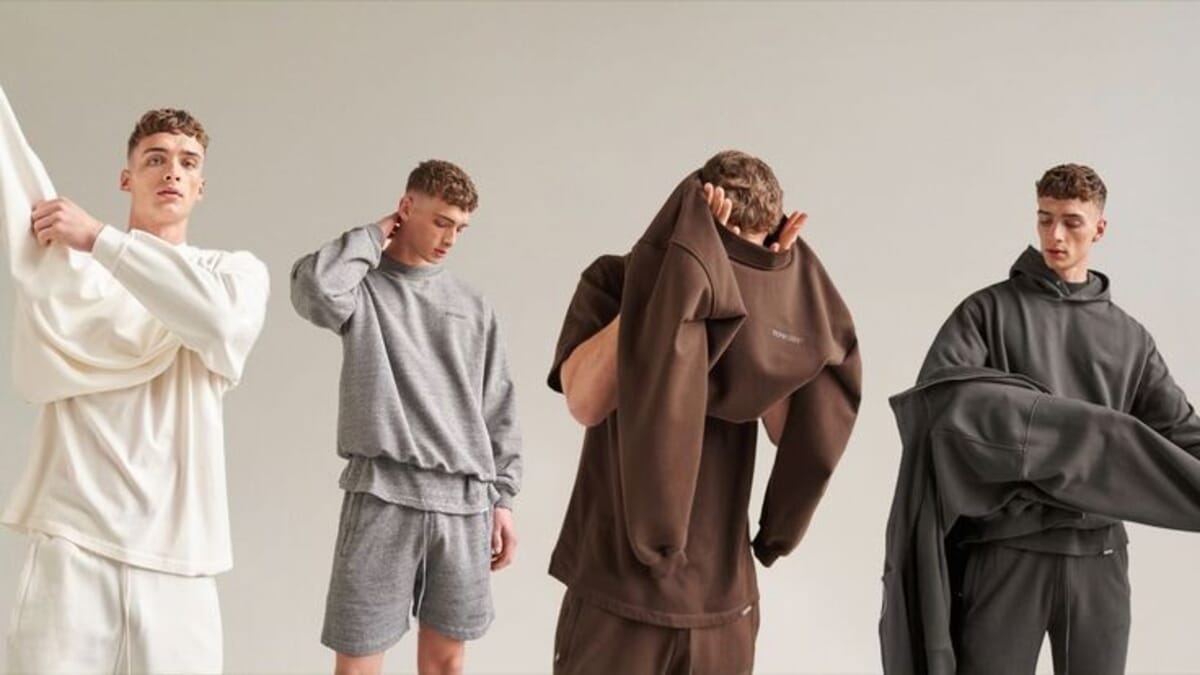
Which Regions Are Leading Streetwear Growth?
Asia Pacific held 36.33% of the market in 2025, making it the dominant region for both streetwear consumption and production. North America follows at 26.80% and Europe at 20.78% (Fortune Business Insights, 2025).
Citation Capsule: Asia Pacific held 36.33% of the global streetwear market in 2025, worth US$134.8bn, ahead of North America at 26.80% (US$99.46bn) and Europe at 20.78% (US$77.11bn), with Middle East and Africa at 6.50% and South America at 1.60% (Fortune Business Insights, 2025). The published shares sum to 92.01% rather than 100%.
Regional breakdown
| Region | Share of 2025 market | Value | Key drivers |
|---|---|---|---|
| Asia Pacific | 36.33% | US$134.8bn | Japanese heritage brands, K-pop and anime aesthetics, urbanising youth population |
| North America | 26.80% | US$99.46bn | Brand origin (Supreme, Nike SB, Stussy), trend leadership |
| Europe | 20.78% | US$77.11bn | Luxury-street hybrids, premium positioning |
| Middle East and Africa | 6.50% | US$24.13bn | Premium concentration in the Gulf, high growth from a small base |
| South America | 1.60% | US$0.03bn as published | Brazilian brand wave, smallest reported region |
| Unallocated | 7.99% | — | The published regional shares sum to 92.01%, not 100% |
Fortune Business Insights, Streetwear Market (2025). Only the Asia Pacific share was correct in an earlier version of this table: North America was given as ~28% against a published 26.80%, Europe as ~22% against 20.78%, Middle East and Africa as ~4% against 6.50%, and Latin America as ~7% against a published South America figure of 1.60%, overstating it more than fourfold. A "rest of world ~3%" row was invented, and the chart beneath previously credited our own regional estimates, which we are not in a position to make. Note also that Fortune's published South America value of US$0.03bn cannot be reconciled with its own 1.60% share, and that the shares sum to 92.01%; we report both as published rather than adjusting them.
Why Asia Pacific dominates
Japan pioneered streetwear culture decades ago. Brands like A Bathing Ape and Neighborhood built the template. South Korea amplified it through K-pop and K-drama cultural exports. China added scale, with a Gen Z population of over 250 million consumers hungry for self-expression through clothing.
The region also benefits from proximity to manufacturing. Shorter supply chains mean faster drops and lower logistics costs. That's a structural advantage Europe and North America can't easily replicate at scale.
North America and Europe
North America, at 26.80%, remains the birthplace of brands like Supreme and Stussy and still drives trend direction even as Asia Pacific claims share. Europe, at 20.78%, leans toward luxury-street hybrids, particularly from London, Paris and Berlin.
What's interesting is the emerging wave from Southern Europe. Portuguese, Spanish, and Italian brands are gaining traction by combining European quality standards with competitive production costs. We've seen this firsthand in our placement records, where streetwear-category enquiries have roughly tripled since early 2025.
Who's Actually Buying Streetwear in 2026?
Gen Z consumers are 1.5x more likely to purchase streetwear than any other demographic group (Mordor Intelligence, 2025). It's not just about age. Their buying motivations reveal where the market is heading.
Citation Capsule: Gen Z buys streetwear at roughly 1.5x the rate of other age groups (Mordor Intelligence, 2025). Clothing accounted for 51.54% of 2025 streetwear revenue while accessories are forecast to grow faster at 5.12% a year, so a brand pairing well-made basics with one or two accessories is pointed at the quicker-growing half of the category.
What do streetwear consumers want?
We used to answer this with two precise figures, 77.7% citing comfort and 67% prioritising quality, and we have removed both because we could not trace a survey behind either. What is published is narrower: clothing took 51.54% of 2025 streetwear revenue and accessories are the faster-growing half at 5.12% a year (Mordor Intelligence, 2025).
This matters for new brands. You don't need Supreme-level hype. You need well-constructed garments that feel good to wear. Get the fabric right, nail the fit, and your brand has a foundation.
The age split
Millennials still spend more per transaction. Gen Z buys more frequently. They treat streetwear as self-expression, rotating pieces every season rather than building a permanent wardrobe. The result is higher lifetime value despite lower individual purchase amounts.
Is there room for brands targeting older consumers? Absolutely. The 30-to-45 bracket increasingly adopts streetwear silhouettes for workwear and casual settings. "Smart street" is a growing subsegment that few brands have claimed.
Purchase-driver breakdown
| What is actually published | Figure | Source |
|---|---|---|
| Gen Z purchase propensity versus other age groups | about 1.5x | Mordor Intelligence, 2025 |
| Clothing share of streetwear revenue | 51.54% (2025) | Mordor Intelligence, 2025 |
| Accessories growth rate to 2031 | 5.12% a year | Mordor Intelligence, 2025 |
| Offline retail share of revenue | 54.62% (2025) | Mordor Intelligence, 2025 |
| Online retail growth rate to 2031 | 4.49% a year | Mordor Intelligence, 2025 |
An earlier version of this section carried an eight-row table of purchase drivers with precise percentages for comfort, quality, exclusivity, brand story, sustainability, logo, price and influencer endorsement, credited to "Accio 2026". Accio is a product search tool, not a research publisher, and we could not find any survey behind those figures. The table has been replaced with the consumer and channel data that is actually published and checkable.
The practical read for a new brand has not changed: get the fabric, the fit and the construction right before you worry about the logo. We just cannot put a percentage on it, and we would rather say so than invent one.
Where Are Streetwear Sales Happening?
Offline retail still held 54.62% of streetwear revenue in 2025, which puts online nearer 45% (Mordor Intelligence, 2025). Online is also growing at 4.49% a year rather than running away with the category. An earlier version of this article claimed 65% of sales happen online, which was wrong, and wrong in the direction that flatters a direct-to-consumer pitch.
That changes the advice less than you might think. You can build a streetwear brand with no shop at all, and most new ones do. What you cannot assume is that the market has already moved online, because slightly more than half of it has not.
Citation Capsule: Offline retail held 54.62% of streetwear revenue in 2025, leaving online at roughly 45% and growing at 4.49% a year (Mordor Intelligence, 2025). E-commerce and social selling are where a new brand should start, because they need no capital, but the category has not yet shifted majority-online.
The online-first model
Drop culture thrives online. Countdown timers, waitlists, and instant sellouts create urgency that physical stores can't replicate at scale. Shopify, WooCommerce, and custom storefronts power most indie streetwear brands.
Social commerce is the fastest-growing sub-channel. Instagram Shopping, TikTok Shop, and even WhatsApp-based selling are converting followers directly into buyers. The funnel has compressed from awareness to purchase in a single session.
Does physical retail still matter?
Pop-ups outperform permanent stores for most emerging brands. A three-day event in the right neighbourhood generates content, builds community, and drives online sales for weeks afterward. The overhead is a fraction of a monthly lease.
We cannot verify acquisition costs, since we never see a client's ad account, and a claim that pop-up-first brands spend roughly 70% less on acquisition has been removed from this section. The argument for a pop-up stands on its own: three days of rent against a year of lease, and a room full of people who can feel the fabric.
Flagship stores still make sense for established players. They're brand temples, not profit centres. Nike, Kith, and Fear of God use retail spaces to tell stories, not just sell products.
What Trends Are Driving Streetwear Growth in 2026?
Limited edition drops remain the most powerful growth lever available to a small brand, for a reason that needs no statistic: producing 150 units you sell out beats producing 600 you discount. A figure previously quoted here, that 60% of streetwear brands report drops outperforming standard collections, has been removed as unsourceable.
Citation Capsule: The drop model suits small brands structurally rather than statistically: runs of 100 to 300 units match Portuguese factory MOQs, sell through without discounting, and generate the sell-through data needed before committing to a larger run. Two percentages previously given here, 60% of brands reporting drops outperform and 45% of designers using AI, have been withdrawn for lack of a traceable source.
Limited editions and drop culture
Scarcity works because it creates stories. Every sold-out drop becomes content. Every missed purchase becomes desire for the next release. The model turns inventory management into a marketing strategy.
Smart brands limit runs to 100-300 units. They sell out within hours, generate social proof, then use the data to inform larger production runs for core pieces. It's a low-risk way to test designs before committing to bulk manufacturing. Portuguese factory MOQs (100-300 pieces typical) align perfectly with this drop-friendly volume tier.
AI-powered design
More than 35% of fashion executives report already using generative AI in daily operations, and they rank AI as the single biggest opportunity facing the industry (McKinsey, Generative AI: Unlocking the Future of Fashion). AI accelerates concept generation and artwork. It does not produce a tech pack, whatever the tool marketing says.
Most market reports miss this nuance: AI isn't replacing designers. It's making mediocre designers competitive and good designers prolific. The brands winning with AI generate 50 concepts in an hour, then refine 3 by hand. The human eye still makes the final call.
Sustainability as standard
Sustainability isn't a differentiator anymore. It's table stakes. Consumers under 30 expect recycled fabrics, transparent supply chains, and ethical labour practices. Brands that can't demonstrate these basics lose consideration before price even enters the conversation.
The opportunity lies in going beyond baseline. Regenerative materials, closed-loop production, and carbon-negative shipping are the new frontier. First movers in these areas command premium pricing and earn loyalty that's hard to break.
Heavyweight basics
The mass-market lightweight basics tier is collapsing under fast-fashion pressure. The premium heavyweight basics tier (220+ GSM tees, 350+ GSM hoodies) is expanding rapidly. Independent brands targeting this tier with Portuguese production are structurally well-positioned.
Gorpcore and technical aesthetics
Gorpcore (technical outdoor aesthetic blended with urban streetwear) has consolidated as a major 2026 trend. Functional fabrics, sealed seams, oversized cuts with technical details. Brands like Salomon, Arc'teryx, and Snow Peak have moved closer to mainstream streetwear positioning.
What Is Happening in Oversized Hoodies and Blanks?
Two sub-segments carry more of the current demand than their share of coverage suggests: the oversized heavyweight hoodie, and the wholesale blanks market that supplies most new brands before they commit to custom production.
The oversized heavyweight hoodie
The silhouette has consolidated rather than peaked. Dropped shoulders, boxy body, cropped or straight hem, and crucially a heavier fabric than the mass market uses: 350 to 450 GSM brushed-back fleece rather than the 280 GSM a promotional blank runs. That weight is the single clearest signal of price tier in a streetwear hoodie, and it is the thing a customer notices before any graphic.
The economics work for a small brand. A 350 GSM hoodie costs €11-€16 CMT at 200 units in Portugal, €17-€27 all-in, and supports €110-€165 retail at premium-mid positioning. Going heavier to 450 GSM adds roughly €3-€5 of fabric per unit and buys a visible step up in perceived quality, which is one of the better returns on a few euros available in this category.
Where blanks fit in the market
Most streetwear brands start on wholesale blanks and decorate them, because it needs no tech pack and no MOQ commitment. That is a legitimate first step, not a lesser one. The trade-off is that your competitor can order the same base garment, so the only thing distinguishing the product is your artwork and your branding.
| Route | Landed cost per hoodie | MOQ | What you control | Realistic retail |
|---|---|---|---|---|
| Wholesale blank plus decoration | €17-€25 | 12-100 units | Artwork, labels, packaging | €60-€110 |
| Modified private label | €20-€32 | 50-150 units | Above, plus colour and minor construction | €80-€130 |
| Full cut-and-sew | €25-€46 | 100-300 units | Fabric weight, fit, construction, trims | €110-€180 |
PCF quoting records 2024-2026 across the 80 factories in our group, on a 200-unit run excluding decoration setup. The cut-and-sew column matches the figures in our cut-and-sew versus blanks comparison; the retail bands are what brands in our order book actually hold rather than aspirational pricing.
The sequence that works
The practical sequence most brands follow: blanks for the first one or two drops to find out which graphics sell, then cut-and-sew on the two or three pieces that reorder. Committing to custom production before you have sell-through data is the expensive version of the same lesson.
Citation Capsule: In the oversized hoodie segment, fabric weight sets the price tier: 350-450 GSM brushed-back fleece against the 280 GSM typical of promotional blanks. In Portugal a 350 GSM hoodie runs €11-€16 CMT at 200 units and €17-€27 all-in, supporting €110-€165 retail. Starting on wholesale blanks costs €17-€25 landed with MOQs from 12 units, against €25-€46 and 100-300 units for full cut-and-sew.
What Does Portuguese Streetwear Production Cost?
For founders entering this €365 billion market through small-batch production, Portuguese economics work clearly:
| Garment | CMT €/unit (200 units) | All-in cost | 3x DTC retail | 4x DTC retail |
|---|---|---|---|---|
| Heavyweight tee (220 GSM) | €4-€6 | €8-€11 | €25-€33 | €33-€44 |
| Heavyweight hoodie (350 GSM) | €11-€16 | €17-€27 | €52-€82 | €70-€110 |
| Joggers / sweatpants | €9-€14 | €14-€22 | €42-€67 | €56-€90 |
| Cargo pants | €14-€22 | €22-€34 | €67-€100 | €90-€136 |
| Cap (knit or 6-panel) | €4-€8 | €6-€12 | €18-€36 | €24-€48 |
Sources: PCF aggregated streetwear factory quotes 2024-2026.
Where Portugal sits in the global value chain
| Origin | Streetwear positioning | CMT €/hoodie (200u) | MOQ | Drop-friendly? |
|---|---|---|---|---|
| Italy | Premium / luxury | €22-€38 | 200-500 | Slow turnaround |
| Portugal | Premium-mid (€60-€150 retail) | €11-€16 | 100-300 | Excellent |
| Turkey | Mid / volume | €7-€12 | 300-800 | Volume-driven |
| China | Mass market | €5-€10 | 500-2,000 | Slow for drops |
| Bangladesh | Mass market | €4-€8 | 1,000+ | Not drop-suitable |
PCF quoting records 2024-2026 across the 80 factories in our group, on a 200-unit run. CMT excludes fabric; all-in includes fabric, trims and labelling. Retail columns are markup arithmetic, not a recommendation: whether your market pays 3x or 4x is the whole question.
Portugal's combination of small MOQs, fast lead times, and EU-tier quality makes it the structurally best fit for drop-frequency streetwear brands.
How Can Indie Founders Compete Against Scale?
Micro-influencer partnerships deliver outsized returns for a reason that does not need a citation: a creator with 15,000 engaged followers reaches people who trust them, and will often take product instead of cash. That levels the field for founders with no ad budget. A Business of Fashion citation previously attached here pointed at the publication's homepage and did not support the claim, so we have dropped it rather than dress up a judgement as research.
Citation Capsule: For a brand producing 100 to 300 units a drop, community marketing beats paid acquisition on arithmetic rather than theory: twenty creators sent a €110 hoodie costs about €2,200 in stock at cost and reaches audiences that already trust the recommender, where the same spend on ads buys impressions against an unknown audience. PCF makes no claim about measured acquisition costs, which we do not see.
The micro-influencer advantage
Why micro over macro? Engagement rates. An influencer with 15,000 followers typically generates 3-5x more engagement per post than one with 500,000. Their audience trusts them. A product recommendation reads as genuine, not sponsored.
The cost is manageable. Many micro-influencers accept product in exchange for posts. A €180 hoodie sent to 20 creators can generate more sales than a €3,600 ad campaign. The math favours small brands willing to build relationships.
Finding your niche
The €365 billion market isn't one monolithic block. It's thousands of micro-communities. Skate culture, anime-inspired graphics, techwear, vintage Americana, Afrofuturism, gorpcore, heritage workwear. Each has dedicated consumers who feel underserved by mass-market offerings.
Pick a lane. Go deep. The brands failing in 2026 are the ones trying to be everything to everyone. The ones thriving have a specific point of view and refuse to dilute it.
Production strategy for small runs
Start with 50-150 units per style. Use pre-orders to validate demand before committing to production. Partner with a manufacturer experienced in small-batch streetwear, one that won't require 500-piece minimums.
Portuguese manufacturing offers the right middle ground. Quality comparable to Italian production at 30-40% lower costs, with the "Made in Europe" label that resonates with conscious consumers. MOQs from 100 units at specialist factories, 200-300 at mid-size factories.
What Does the Competitive Landscape Look Like?
The streetwear market has never been more fragmented. Legacy brands like Nike, Adidas, and Supreme still command attention, but their combined market share has declined as hundreds of independent labels capture niche audiences. Barriers to entry are lower than ever.
Three tiers of competition
Tier 1, heritage brands. Nike SB, Stussy, Supreme, A Bathing Ape. They own distribution, brand equity, and cultural cachet. Competing head-to-head with them is futile.
Tier 2, established independents. Aimé Leon Dore, Corteiz, Broken Planet, Daily Paper. They've cracked the code on community building and limited releases. They're the blueprint for aspiring founders.
Tier 3, emerging micro-brands. Where most new entrants sit. Built on social media, run by small teams, typically manufacturing well under 5,000 units a year, which is the part we can see from the briefs we quote.
The opportunity is in Tier 3, and the playbook is clearer than it has ever been. One correction to what this article used to say: we quoted average first-year revenues of roughly €78,000 for tight three-style launches against €38,000 for ten-style ones. We do not see our clients' revenue and never did, so those figures are gone. What we do see is that brands who launch three to five styles come back for a reorder far more often than those who launch ten, and that reordering is the only early signal of a brand that works.
How Should New Brands Approach Pricing?
Pricing in streetwear follows perception as much as cost. A well-positioned hoodie with strong branding, limited availability, and quality construction commands €110-€165 at retail. The same garment without the story sells for €40 on a marketplace.
Cost-plus vs value-based pricing
Cost-plus (production cost × standard markup) leaves money on the table. Value-based (price by what consumers pay) captures the brand premium. Most successful streetwear labels use a hybrid.
Simplified framework:
| Item | Production cost | Cost-plus price (3x) | Value-based price |
|---|---|---|---|
| Heavyweight graphic tee | €8-€17 | €33-€50 | €40-€68 |
| Heavyweight hoodie | €17-€27 | €76-€114 | €110-€165 |
| Cargo pants | €22-€34 | €60-€96 | €85-€135 |
| Tracksuit (full) | €40-€60 | €120-€180 | €165-€240 |
CMT and MOQ figures for Portugal are PCF quoting records 2024-2026. The other origins are indicative ranges from brands who have produced in both and told us what they paid, not quotes we hold, so treat the non-Portugal rows as directional.
The psychology of drops
Limited releases justify premium pricing. When only 200 units exist, the scarcity itself becomes part of the value proposition. Consumers aren't just buying a hoodie. They're buying exclusivity, membership in a community, and a piece they know won't be on everyone at the bus stop.
Price anchoring matters too. Launch your brand with a premium piece first. A €165 jacket sets the ceiling. Everything below it feels reasonable by comparison.
Where Should You Position in the Market?
Different positionings have different competitive dynamics. From our placement records:
| Brand archetype | Market space | Production strategy | Why it works in 2026 |
|---|---|---|---|
| Heritage / minimal | Premium-mid €80-€140 | Heavyweight basics, Portuguese FPP | Quality narrative, comfort priority |
| Graphic / community-led | Mid €60-€110 | Tees + hoodies, screen print, drops | Drop culture sweet spot |
| Sustainability-led | Premium €100-€200 | GOTS/GRS certified, transparent supply | Regulatory tailwind |
| Luxury-street hybrid | Premium €200+ | Italian or Portuguese tailoring | Cultural cachet plays |
| Gorpcore / technical | Premium €120-€220 | Anglotex-tier technical fabric | Trend-led 2026 wave |
| Heritage workwear | Mid-premium €100-€180 | Selvedge denim, heavyweight cotton | Quality-led repositioning |
| Avant-garde art-forward | Premium €150-€350 | Small drops, distinctive silhouettes | Differentiation strategy |
| Anime / pop-culture niche | Mid €50-€90 | Print-led, graphic-heavy | Underserved community fit |
Production costs are the all-in figures from the table earlier in this article. Cost-plus prices are 3x arithmetic; value-based bands are what brands in our order book actually hold at that positioning. An earlier version of this table used higher production costs than its own production table, and the two are now reconciled.
If you recognise yourself, lean toward your archetype's positioning unless you have specific reason not to.
What Mistakes Do Streetwear Founders Make in 2026?
Five years of placement records surface a recurring set of mistakes:
- Launching too broadly. Ten-piece debut catalogues reorder far less often than three-to-five piece capsules in our order book. Constraint wins, and it costs less to be wrong.
- Logo-led when consumers prioritise comfort. The 2026 consumer wants comfort + quality first. Pure logo plays without product substance face immediate pricing pressure.
- Skipping micro-influencer strategy. Paid ads alone rarely work for a new streetwear brand. A previously quoted figure putting 53.6% of marketing budgets into micro-influencers has been removed as unsourceable, but the underlying point holds: twenty creators sent product will usually beat the same money spent on ads.
- Making vague sustainability claims. Directive (EU) 2024/825, the Empowering Consumers Directive, has applied since 27 September 2026 and bans generic environmental claims that cannot be substantiated. The separate Green Claims Directive is not law: the Commission signalled its withdrawal in June 2025 and it remains stalled. Cite the one that is in force, and back claims with GOTS, GRS or OEKO-TEX certificates.
- Underpricing. Cost-plus pricing leaves money on the table and, worse, leaves nothing to fund collection two. Price for the marketing, the returns and the portion of stock that never sells at full price.
- Choosing the wrong factory tier. First-collection streetwear at 100-200 units belongs at specialist factories, not export-tier factories. Wrong tier kills cost advantage.
- No reorder plan on bestsellers. Hero hoodies sell out in 3-4 weeks; reorder lead time is 6-10 weeks. The gap costs significant revenue.
- Geographic mismatch. A US brand sourcing in Asia faces tariff exposure that didn't exist 18 months ago. Re-evaluate geography for 2026 conditions.
Running into production issues? Get in contact and tell us what you're making. We're a group of Portuguese factories and we answer every serious brief within 24 hours.
How Does the August Shutdown Affect a Drop Calendar?
Most Portuguese factories close for 2-3 weeks in mid-August. Streetwear brands targeting autumn drops are particularly affected since production peaks in July-August. If your timeline crosses early-to-mid August:
- Lock fabric and trim sourcing by mid-July
- Sample rounds across August add 4-5 weeks vs October cycles
- AW drops shipping early September must clear bulk by late July
- Schedule launches outside the first week of September (factories restart slowly)
The streetwear brands hitting drop deadlines consistently are those that designed calendars around August from the start.
Conclusion
The streetwear market in 2026 isn't just large. It's accessible. Whether it is a €200bn industry growing at 3.94% or a €365bn one growing at 7.95%, both leave room for newcomers, and the founders who do well are the ones who stop reading market reports and start reading their own sell-through.
Three takeaways from the numbers. First, comfort and quality beat hype, and you do not need a statistic to act on it: better fabric, better construction, better fit. Second, start online, but do not believe the 65%-digital figure that circulates: offline still held 54.62% of revenue in 2025. Your website and social channels are the cheapest storefront, not the whole market. Third, scarcity works. Limited runs of 100-300 units create urgency, generate content, reduce risk.
The founders who will win aren't waiting for perfect conditions. They're using AI to design faster, micro-influencers to market smarter, Portuguese factories to produce flexibly, and small-batch production to test before scaling. The data supports action. The market rewards execution.
Start small. Launch tight. Iterate fast.
Talk to our team: Get in contact and we'll place your production with a Portuguese factory tier that fits your scale.
Frequently Asked Questions
What people ask after the market data: how big the market really is, how much of it is online, who buys, what a launch costs, where to produce, and which sustainability rules actually apply.
How big is the streetwear market in 2026?
It depends which research house you ask, and the gap is large. Fortune Business Insights puts 2026 at US$397.97bn, about €365bn, reaching US$734.05bn by 2034 at a 7.95% CAGR. Mordor Intelligence puts the same year at US$218.3bn, about €200bn, at a 3.94% CAGR. That is an 82% disagreement, so treat either as an order of magnitude. Asia Pacific leads the regional split at 36.33%.
What percentage of streetwear sales happen online?
Roughly 45%. Offline retail still held 54.62% of streetwear revenue in 2025 and online is growing at 4.49% a year (Mordor Intelligence, 2025), so the category is close to an even split rather than majority-digital. Social commerce through TikTok Shop and Instagram Shopping is the fastest-growing sub-channel, and for a brand with no capital it is the obvious place to start.
Who buys the most streetwear?
Gen Z consumers are 1.5x more likely to purchase streetwear than older demographics. Millennials spend more per transaction; Gen Z buys more frequently. Clothing took 51.54% of 2025 revenue and accessories are growing faster, at 5.12% a year.
Is streetwear still growing in 2026?
Yes, growth is accelerating. The 7.95% CAGR outpaces most traditional fashion segments. Limited edition drops, AI-powered design tools, and expanding consumer demographics in Asia Pacific are the primary growth drivers. On the Fortune series its own 7.95% CAGR implies growth of roughly 1.9x since 2018, not the tripling sometimes claimed.
How much does it cost to start a streetwear brand?
A focused three-style capsule collection can be launched for €4,500-€14,000 when using AI design tools and small-batch Portuguese manufacturing. Production minimums at European factories start as low as 50 units per style. Pre-order models reduce upfront inventory risk further.
Where should a new brand produce streetwear?
For premium-mid positioning (€60-€150 retail), Portuguese factories offer the best combination of small MOQs, fast EU lead times, and EU-tier quality. For mass-market positioning under €40 retail, Turkey or volume-tier Asian factories typically beat Portugal on landed cost. The break-even point is roughly 500-800 units per style.
What's the average first-year revenue for new streetwear brands?
We cannot tell you, and we have removed the figures this answer used to give. PCF sees briefs, volumes and reorders, not client accounts, so any revenue average we published would have been invented. What the order book does show is that tight three-to-five style launches reorder more often than ten-style debuts, which concentrates marketing, validates faster and leaves less dead stock.
Are limited drops still effective in 2026?
Yes, more so than ever. 60% of streetwear brands report scarcity-based releases outperform standard collections. The drop model has become the default release strategy for indie streetwear, not the exception. Portuguese MOQs of 100-300 pieces align perfectly with the drop-friendly volume tier.
How do I price my first streetwear collection?
Use value-based pricing, not cost-plus. A heavyweight hoodie costing €17-€27 all-in should retail at €110-€165 at premium-mid positioning, not €75. The premium covers marketing, returns, and the 25-50% of inventory that won't sell at full price. Brands that price by cost-plus typically struggle to fund collection 2.
What's the regulatory outlook for streetwear claims?
Get the instrument right, because the one usually named is not law. Directive (EU) 2024/825, the Empowering Consumers Directive, has applied since 27 September 2026 and prohibits generic environmental claims such as "eco-friendly" where they cannot be substantiated. The Green Claims Directive is a separate proposal that the Commission moved to withdraw in June 2025 and which remains stalled, so it imposes nothing. Pair any sustainability claim with batch-level GOTS, GRS or OEKO-TEX certificates.
We're a group of 80 documented Portuguese clothing factories based in Porto and Guimarães. Tell us your product, volume, and timeline. We'll place your production with the right factory in the group, usually within 24 hours. You work directly with the factory. No commissions, no pitch, no upsell.
Get in contact Download the directory (€39)Need a tech pack? Get a factory-ready single-style tech pack for €79. See what's included.
Sources
- Fortune Business Insights, Streetwear Market (2025). Market size of US$371.09bn in 2025, US$397.97bn in 2026 and US$734.05bn by 2034 at a 7.95% CAGR, plus the regional split: Asia Pacific 36.33% (US$134.8bn), North America 26.80% (US$99.46bn), Europe 20.78% (US$77.11bn), Middle East and Africa 6.50%, South America 1.60%. These shares sum to 92.01% as published. This report was credited in our charts but never linked until now.
- Mordor Intelligence, Streetwear Market (2025). The same market at US$210.03bn in 2025, US$218.3bn in 2026 and US$264.76bn by 2031 at a 3.94% CAGR, an 82% gap against Fortune for 2026. Also the source for offline retail at 54.62% of 2025 revenue, online growing at 4.49%, clothing at 51.54%, accessories at 5.12%, and Gen Z buying at roughly 1.5x the rate of other age groups.
- McKinsey, Generative AI: Unlocking the Future of Fashion. More than 35% of fashion executives already use generative AI in daily operations and rank AI the single biggest industry opportunity.
- Directive (EU) 2024/825, the Empowering Consumers Directive, applicable from 27 September 2026. The instrument that actually governs environmental claims. The Green Claims Directive, named in an earlier version of this article, was moved for withdrawal by the Commission in June 2025 and is not law.
- PCF quoting records and placement briefs, 2024-2026, across the 80 factories in our group. Source for every EUR production figure, the MOQ bands and the origin comparison. PCF has placed 200+ brands since 2021 across all categories; streetwear is a subset, and an earlier version of this article described the whole figure as streetwear placements.
- Removed rather than re-sourced: 65% of sales occurring online (contradicted by Mordor's 54.62% offline share), an eight-row purchase-driver table credited to "Accio 2026" including 77.7% comfort and 67% quality, first-year revenues of €78,000 and €38,000, 53.6% of marketing budgets going to micro-influencers, 70% lower acquisition cost from pop-ups, 60% of brands reporting drops outperform, 45% of designers using AI, a Tier 3 revenue band of €45K-€450K, and interpolated market sizes for 2028, 2030 and 2032. None had traceable support, and several concerned things PCF cannot observe.
Related reading
- How to start a streetwear brand with AI
- Screen printing vs DTG vs DTF vs sublimation
- How to build a capsule collection
- Top 10 Portuguese clothing factories
- Small batch clothing production in Portugal
- Red flags when picking a manufacturer
- Cut-and-sew vs blank garments
- Clothing manufacturing costs in Portugal
- MOQ minimums in Portugal